Rate and term
Record APY, term, minimum deposit, balance cap, compounding, and whether the rate is fixed.
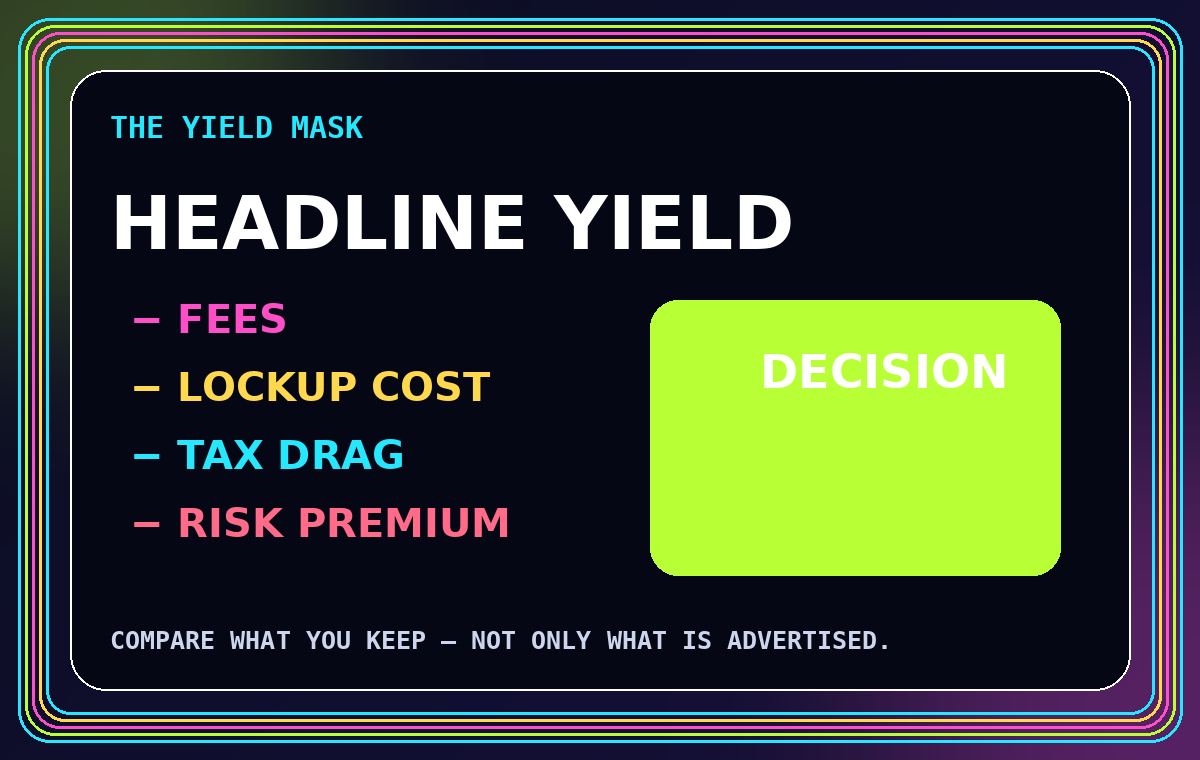
A certificate of deposit can convert idle cash into a defined interest schedule, but the advertised APY is only one part of the contract. Use the Yield Mask to compare access, penalties, insured ownership, maturity dates, and renewal rules alongside rate.
Use the same comparison order every time: define the rate, translate it into dollars, map access, subtract friction, and identify the risk engine.
Record APY, term, minimum deposit, balance cap, compounding, and whether the rate is fixed.
Estimate proceeds under an early exit. Some penalties can exceed accrued interest or require closing the entire CD.
Combine eligible balances at the same insured institution and ownership category rather than counting account titles.
Put the maturity and grace-period deadline on a calendar. Automatic renewal is a default, not a recommendation.
Stagger maturities to create access points and reduce the risk of committing all cash at one rate.
Keep separate cash for near-term needs so a modest rate advantage does not create expensive access problems.
These fields turn unlike product pages into a common worksheet. The table is educational and contains no live quotes.
| CD feature | Question to ask | Decision-yield effect |
|---|---|---|
| APY | Which balance and term qualify? | Sets gross interest estimate |
| Early withdrawal | How is the penalty calculated? | Reduces or can invade proceeds |
| Insurance | What is the issuing bank and ownership category? | Changes loss protection |
| Renewal | What term and rate apply after the grace period? | Can create an accidental lockup |
| Interest payout | Paid out or added to principal? | Changes cash flow and compounding |
Each guide uses one authoritative external reference and links the mechanism back to practical comparison fields.
A practical framework for comparing certificate of deposit APY, term length, insurance, renewal rules, and the real cost of locking cash.
Read the guide
Compare direct Treasury bills with Treasury and government money market funds across yield quotes, maturity, liquidity, fees, reinvestment, and account mechanics.
Read the guide
A business cash-management checklist for evaluating interest-bearing checking, balance tiers, fees, sweep programs, deposit insurance, and access rules.
Read the guideCD yield is commonly presented as APY, which annualizes interest with compounding assumptions. Your actual dollars depend on principal, term, dates, and withdrawals.
A fixed-rate CD generally states a rate for its term, subject to the account contract. Specialty CDs can have different mechanics, so read the disclosure.
Eligible deposits at an insured institution may have deposit-insurance protection within applicable limits, but early-withdrawal penalties and nonstandard structures can affect proceeds.